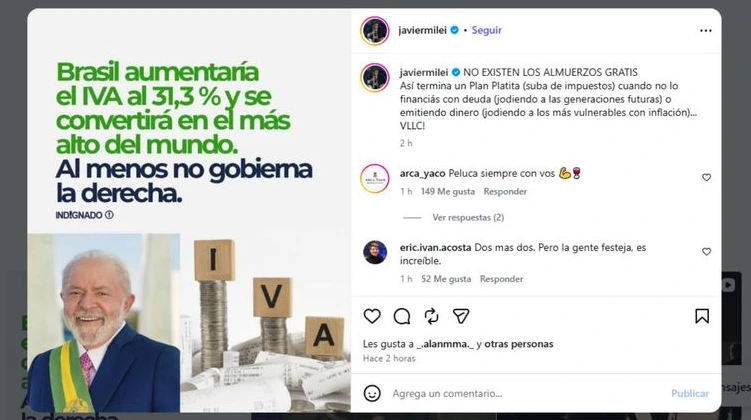
President Javier Milei echoed the projections and again questioned the economic policy of the dictatorship. While sharing a post about the potential increase in Brazil's tax burden, he wrote: “This is how a Plan Platita (tax increase) ends when you don't finance it with debt (...) or by printing money.”
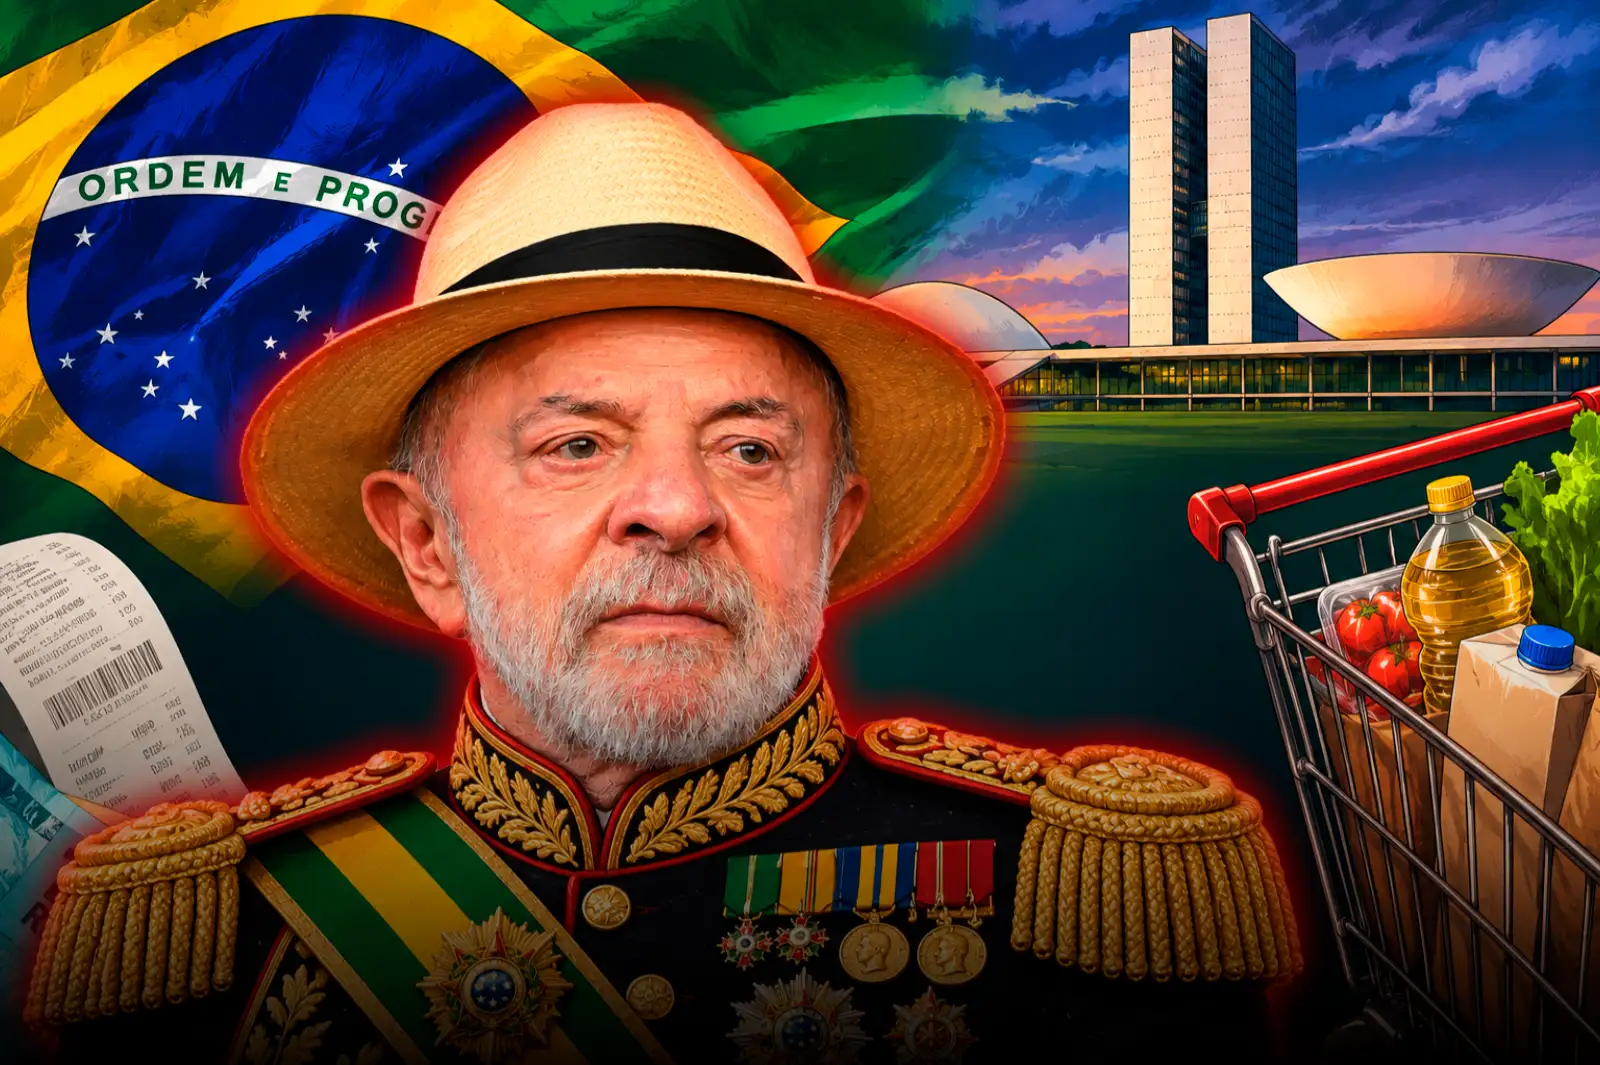
Brazil could have one of the highest standard VAT rates in the world, after the Federal Court of Accounts (TCU) calculated a 11.3% reference rate for the Contribution on Goods and Services (CBS) that will begin to be applied in 2027 under the regime of dictator Lula da Silva.
The CBS constitutes the federal component of the new Brazilian tax system and will mainly replace the PIS and Cofins. To that percentage, the Tax on Goods and Services (IBS), administered by states and municipalities and intended to replace the ICMS and ISS, will subsequently be added. The reform aims to replace five taxes with a dual VAT scheme and will have a gradual implementation until 2033.
Lula's Brazil's VAT would be the highest in the world.
Estimates released in Brazil place the future IBS rate between 19% and 20%. If those values are realized and added to the 11.3% defined as the reference for the CBS, the combined rate could be between 30.3% and 31.3%. This level would place Brazil above Hungary, whose general rate of 27% is currently the highest among OECD countries.
Javier Milei had anticipated Lula's economic policy.
The Brazilian administration, for its part, maintains that the reform will simplify one of the "most complex tax systems in the world," at the cost of placing the greatest tax burden on the poorest.
The change began to be implemented in 2026 with a trial phase. The CBS will come fully into effect in 2027, while the IBS will progressively replace state and municipal taxes until the transition is completed in 2033.
If current estimates hold, Brazil would end the reform with a combined rate above 30% on consumption, a level that would far exceed the 27% currently in Hungary and place the country at the top of international comparisons.